A Better Way to Value Bus Cap
Bus Cap Berhad deserves to be analysed as a sustainable-growth manufacturing company, not merely as a short-term IPO trading counter. The Company gives Bursa Malaysia investors a rare pure-play exposure to the bus manufacturing value chain, supported by an existing earnings base, established production know-how and a clear reinvestment plan into capacity and production efficiency.
At the IPO price of RM0.230, Bus Cap was valued at approximately RM88.2 million market capitalisation. Based on FY2025 PAT of RM9.81 million, the IPO valuation was undemanding at around 9.0x historical earnings. The more relevant discussion now is whether the stock can be fairly supported at RM0.500 without relying on an overly aggressive valuation multiple.
Our view is positive. A RM0.500 valuation is defendable if investors price Bus Cap on a more sustainable forward earnings base of around RM12.0 million PAT, rather than only on FY2025 historical earnings. This is the key difference: RM0.500 should not be framed as a high-PE momentum target; it should be framed as a forward earnings normalisation target backed by semi-automation, process engineering and better production throughput.
Backward Valuation: What RM0.500 Actually Implies
Based on an estimated enlarged share base of approximately 383.4 million shares, RM0.500 per share implies a market capitalisation of approximately RM191.7 million. On FY2025 PAT of RM9.81 million, this would translate into about 19.5x PE, which may look full if viewed only from a historical earnings angle. However, this is not the most constructive way to value a company that is raising capital to expand capacity and improve production efficiency.
The more practical valuation question is: what forward PAT does Bus Cap need to make RM0.500 look reasonable? The answer is approximately RM12.0 million. At RM12.0 million PAT, Bus Cap would generate forward EPS of about 3.13 sen, and RM0.500 would imply a forward PE of only around 16.0x. This is a more measured valuation level, especially for a company with a profitable base, high capacity utilisation and a defined pathway to incremental output.
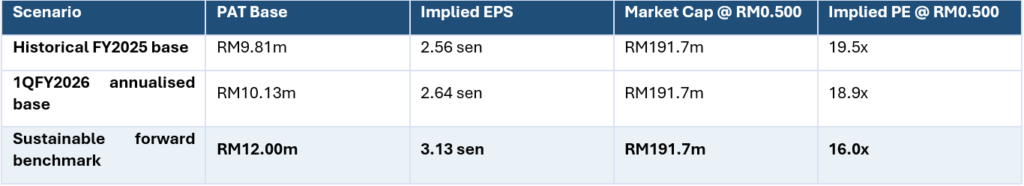
his backward calculation is important because it anchors the RM0.500 discussion in earnings delivery rather than market excitement. The valuation becomes far more investable when the market believes Bus Cap can move from a RM9.8 million historical PAT base toward a RM12.0 million forward PAT base.
Why RM12 Million PAT Is a More Sustainable Benchmark
The RM12.0 million PAT benchmark is not an unrealistic earnings leap. Bus Cap has already shown a profitable baseline. For FY2025, the Company recorded RM88.08 million revenue and RM9.81 million PAT, supported by the delivery of 131 buses and a production utilisation rate of about 78% against an annual capacity of 168 buses.
Its 1QFY2026 performance also provides a useful reference point. Bus Cap recorded RM19.28 million revenue and RM2.53 million PAT for the quarter ended 31 March 2026. On a simple annualised basis, this points to approximately RM10.1 million PAT before fully factoring in the intended benefit from IPO-funded expansion, semi-automated fabrication lines and process improvements.
From this perspective, the move toward RM12.0 million PAT is not about assuming a sudden spike in demand or a speculative margin expansion. It is more about incremental improvements: better production flow, reduced manual bottlenecks, more consistent fabrication, improved scheduling discipline, higher throughput and tighter cost control. These are precisely the areas where semi-automation and process engineering can create measurable value.
Semi-Automation and Process Engineering: The Real Re-Rating Driver
The most positive part of Bus Cap’s story is that its growth strategy is operational rather than promotional. The Company is not trying to reinvent its business model. Instead, it is using IPO proceeds to strengthen its manufacturing platform through a new production facility, semi-automated fabrication machinery and working capital support.
This matters because bus manufacturing is execution-heavy. Earnings growth is not driven by branding alone; it comes from cycle time, labour productivity, chassis availability, fabrication accuracy, quality consistency and delivery scheduling. Semi-automation can help standardise key production stages, while process engineering can reduce inefficiencies across the workflow. In practical terms, that means Bus Cap may be able to deliver more buses with better cost discipline and fewer production bottlenecks.
The planned expansion is also sensible in scale. Public information indicates that annual capacity is expected to increase by approximately 15%, from 168 buses to 194 buses. This is not an overly aggressive capacity jump that risks underutilisation. Instead, it is a measured expansion from an already high utilisation base. For investors, that makes the growth profile more sustainable and easier to underwrite.
Demand Is Supported by Replacement and Mobility Needs
The demand backdrop also supports a positive view. Bus Cap is exposed to a market that benefits from fleet replacement, intercity travel, tourism recovery, cross-border movement and the broader need to improve public transport availability. This is important because bus demand is not purely discretionary; operators eventually need to maintain, upgrade or replace fleets to remain commercially and operationally relevant.
This gives Bus Cap a more durable demand profile compared with companies that depend on one-off construction contracts or single-project recognition. Fleet replacement is not a straight-line cycle, but it is recurring over time. When combined with higher-capacity bus demand, tourism normalisation and public transport focus, Bus Cap has a credible pathway to maintain order flow and gradually scale earnings.
Investment View: RM0.500 Is Reasonable If Execution Remains Intact
A RM0.500 valuation should be interpreted as a sustainable growth benchmark rather than a speculative target. At that level, the stock would not need to command a stretched 20x-plus forward valuation if Bus Cap can deliver RM12.0 million PAT. Instead, the implied forward PE would sit at around 16.0x, which is more acceptable for a profitable niche manufacturer with visible capacity expansion and efficiency upside.
The most important re-rating factor is earnings delivery. If Bus Cap can convert its semi-automation and process engineering initiatives into higher throughput, improved cost control and stronger delivery momentum, the market should become more comfortable valuing the Company on forward earnings. In that scenario, RM0.500 becomes less of an ambitious price level and more of a reasonable reflection of the Company’s next earnings base.
From an analyst’s lens, the stock deserves a more constructive valuation because the growth drivers are tangible: capacity expansion, production efficiency, steady replacement demand and existing profitability. The Company is not starting from zero; it is building from a profitable base. That distinction is important.
Key Risks to Monitor
The main risks are execution-related. Investors should monitor whether Bus Cap can roll out its semi-automation plan on schedule, preserve margins amid raw material and labour cost movements, secure sufficient chassis supply, and maintain healthy order momentum from bus operators. A delay in capacity expansion or weaker-than-expected utilisation would reduce the strength of the RM12.0 million PAT argument.
That said, these risks are manageable and typical for a manufacturing growth company. They do not undermine the broader thesis as long as Bus Cap continues to show disciplined execution and quarterly earnings remain on an upward path.
Conclusion
Bus Cap deserves to be positioned as a sustainable growth story. The RM0.500 valuation case does not require an excessive PE multiple. It only requires the market to believe that the Company can lift its forward PAT base toward RM12.0 million through semi-automation, process engineering and better capacity utilisation.
At RM12.0 million PAT, RM0.500 implies about 16.0x forward earnings. For a profitable, niche bus manufacturer with a defined expansion plan and recurring replacement-driven demand, this valuation is reasonable. The upside case is therefore not built on hype, but on execution. If Bus Cap delivers the earnings progression, RM0.500 is a fair and achievable valuation milestone.
Internal data reference note: Key historical and operating figures are based on publicly available IPO prospectus reporting, Bursa quarterly reporting and mainstream financial media coverage available as at 3 June 2026. The RM12.0 million PAT figure is used as a forward valuation benchmark for this article.
